A three-year-old company that writes legal memos with AI is now worth more than most of the law firms it sells to.
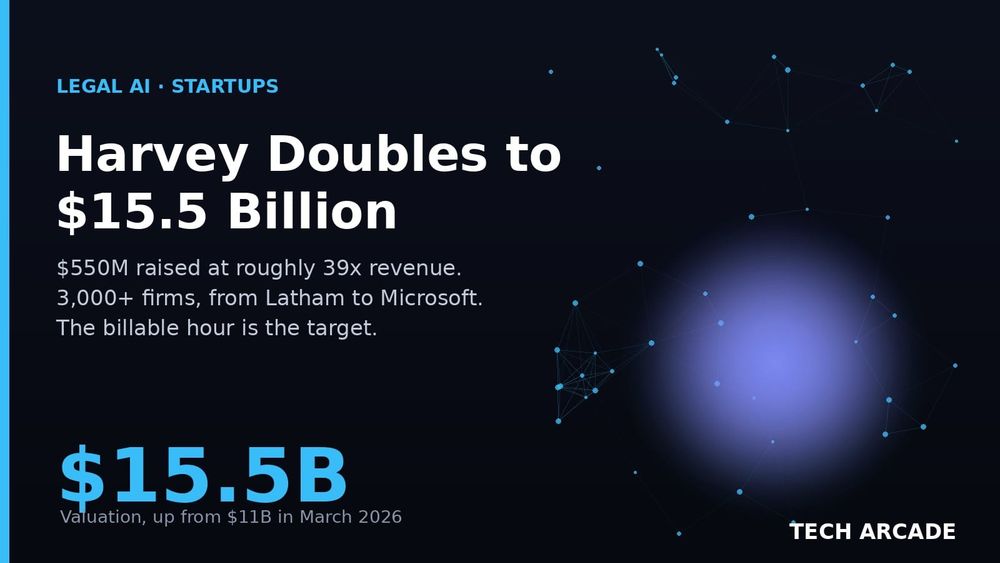
Let's get the number on the table first: $550 million. That's the fresh cash Harvey, the San Francisco legal-AI startup, just raised in a round co-led by Lightspeed Venture Partners and Diffusion. The round values the company at roughly $15.5 billion, up from $11 billion in March (TechCrunch). Bloomberg pegs the figure a hair higher at $15.6 billion (Bloomberg).
Either way, the valuation has doubled in six months. Rewind a little further and it gets dizzier: Harvey was worth $3 billion in February 2025, $8 billion by December, $11 billion in March, and $15.5 billion now (Tech Startups). Five priced valuations in nineteen months, each one bigger than the last.
Here's the thesis: the market isn't paying for a legal-software company. It's paying for a bet that AI eats billable hours.
🧠 Why This Matters
Law is one of the most expensive knowledge industries on earth, and almost all of that cost is a human being reading documents. Contract review, due diligence, discovery, research memos — the grunt work that junior associates bill out at hundreds of dollars an hour is exactly the kind of pattern-matching large language models are unnervingly good at.
Harvey's pitch is that it can do that work faster and cheaper, and law firms are buying it. The company now reports $400 million in annual recurring revenue, up from roughly $100 million at the start of the year (LawSites). It claims 80% of the top 100 U.S. law firms as customers, plus 20% of the Fortune 500 and half of the Fortune 10.
When four out of five of the biggest firms in the country are paying you, you've stopped being an experiment and started being infrastructure. That's the story investors are underwriting.
📊 Deep Dive
The customer curve is the part that makes VCs open their wallets. Harvey went from about 1,300 organizations earlier this year to more than 3,000 today — more than doubling its base in a few months (Tech Startups). The named logos are the ones that matter in this industry: Latham & Watkins, and Microsoft's own legal team.
Where the money goes is telling. Cofounder Winston Weinberg said the capital is going into the two things that actually move the needle:
"[It] is being invested into our two most important resources: people and compute." — Winston Weinberg, Harvey cofounder (LawSites)
"Compute" is the word to watch. Harvey started as a wrapper on other companies' models. It's now building its own. This summer it launched Tenet, an in-house model post-trained on legal data from an open-weight base, plus Harvey LAB, its own benchmark for grading how well AI handles legal work. Owning the model stack is how you stop paying rent to a foundation-model provider on every query.
How the round stacks up against the recent run:
- This round: $550M raised, ~$15.5B valuation, ~$400M ARR
- March 2026: $200M raised, $11B valuation
- December 2025: $8B valuation
- February 2025: $3B valuation
- Total raised since 2022: north of $1.5 billion across at least eight priced rounds (LawSites)
The investor list reads like a Sand Hill Road roll call: alongside Lightspeed and Diffusion sit Sequoia, Kleiner Perkins, a16z, Coatue, GIC, and Goldman Sachs Alternatives (LawSites).
⚠️ The Catch
Do the division and you get the number that should give you pause. At $400 million in revenue and a $15.5 billion price tag, Harvey is valued at roughly 39 times its annual recurring revenue (Tech Startups). Traditional enterprise software companies trade at single digits to low teens. Harvey is priced at nearly triple that, which only pencils out if you believe its revenue keeps compounding at the pace of the last year rather than the pace of a normal software business.
The competition is real and well-funded. Swedish rival Legora is reportedly chasing a valuation north of $10 billion. And the incumbents — LexisNexis and Thomson Reuters — already sit inside every firm Harvey wants to win, with decades of proprietary legal data and existing contracts. Harvey has speed; they have the moat.
Then there's the product risk that never fully goes away: language models still make things up, and a hallucinated case citation in a court filing isn't a bug, it's a sanctionable offense. Lawyers have already been fined for it. Selling AI into a profession where being wrong has legal consequences is a harder sell than selling it into marketing.
🎯 What Happens Next
Harvey has said it plans to push beyond research memos into contracting, litigation, deals, and compliance — the deeper, higher-value workflows where the real billable dollars live. That expansion is what the $550 million is meant to fund.
Watch the ARR number. If Harvey exits the year meaningfully above $400 million, the 39x multiple starts looking like foresight. If growth cools, this becomes the round people point to when they talk about AI froth. The next twelve months settle which story is true.
🧩 Bigger Picture
Harvey isn't an isolated bet. It's part of a wave of "vertical AI" companies aiming a language model at one expensive profession and charging like a software company while replacing the economics of a labor one. The same script is playing out in coding, in medicine, in accounting.
What makes law the sharpest test is that its entire pricing model — the billable hour — assumes a human spends time. If AI collapses the time, it collapses the bill. Harvey's investors are betting the firms would rather own that disruption than be flattened by it. At $15.5 billion, they're betting a lot.
The pyramid of junior associates reading documents at 2 a.m. was always the strangest part of how law made money. Harvey just raised half a billion dollars to find out what the profession looks like without it.
Sources
- TechCrunch — Harvey hits $15.5B valuation, months after reaching $11B
- Bloomberg — Legal AI Startup Harvey Hits $15.6 Billion Value With $550 Million Round
- LawSites — Harvey Raises Another $550M At A $15.5B Valuation
- Tech Startups — Legal AI startup Harvey raises $550M at $15.6B valuation as revenue tops $400M